Days sales outstanding (DSO) is a financial metric that measures the average number of days a company takes to collect payment after making a credit sale. It shows how quickly accounts receivable turns into cash and is calculated as (Accounts receivable ÷ Total credit sales) × Number of days in the period. A lower DSO means customers pay faster and more cash is available; a higher DSO signals collection delays, invoicing problems or credit risk.
Global average DSO
56.5 days
2025 · Allianz Trade, July 2026
Global cash conversion cycle
67 days
2025 · Allianz Trade, July 2026
Cash tied up per DSO day
~$2.7M
Per $1B annual credit sales ($1B ÷ 365)
Days Sales Outstanding (DSO) at a Glance
| Item | Answer |
|---|---|
| Definition | Average number of days to collect payment after a credit sale |
| Formula | DSO = (Accounts receivable ÷ Total credit sales) × Number of days |
| Measures | Collection speed, accounts receivable efficiency and cash flow health |
| Lower DSO | Faster collections and stronger liquidity |
| Higher DSO | Late payments, disputes, invoicing delays or loose credit terms |
| Good DSO | Within 10–15% of your payment terms (Best Possible DSO) |
| Related metrics | Average days delinquent (ADD), AR turnover, cash conversion cycle (CCC) |
How to Calculate DSO
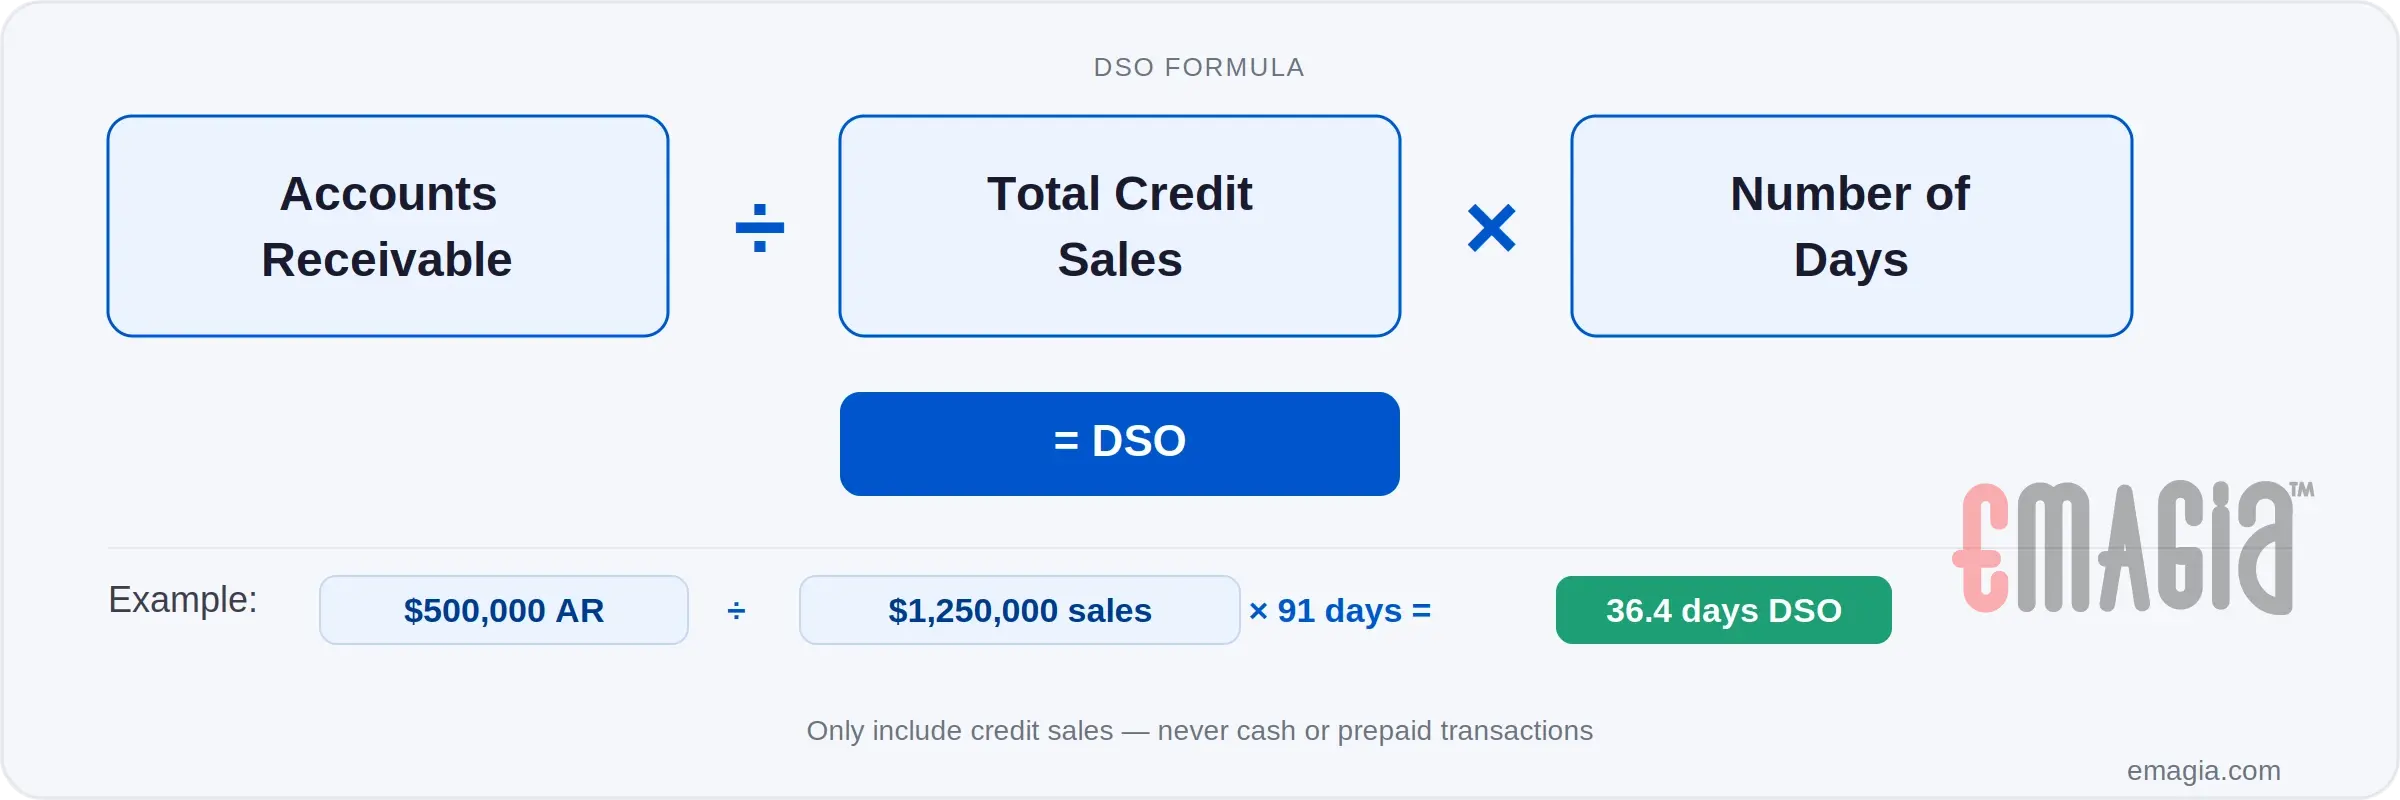
DSO = (Accounts Receivable ÷ Total Credit Sales) × Number of Days in the Period
- Take accounts receivable at the end of the period.
- Take total credit sales for the same period. Exclude cash sales and prepayments.
- Divide accounts receivable by credit sales.
- Multiply by the number of days in the period (for example 30 or 31 for a month, 90 or 91 for a quarter, 365 for a year).
Some companies use average accounts receivable ((beginning AR + ending AR) ÷ 2) instead of ending AR to smooth out month-end swings. Either approach is valid; use the same one every period so trends are comparable.
DSO Calculation Example
| Metric | Value |
|---|---|
| Total credit sales (quarter) | $1,250,000 |
| Accounts receivable (end of quarter) | $500,000 |
| Days in period | 91 |
| DSO | ($500,000 ÷ $1,250,000) × 91 = 36.4 days |
If accounts receivable were $850,000 on the same sales, DSO would be ($850,000 ÷ $1,250,000) × 91 = 61.9 days. Whether that is a problem depends on payment terms: on Net 60 terms it is close to on time, while on Net 30 terms customers are paying about a month late.
Countback Method: A More Accurate DSO for Seasonal Businesses
The standard formula can distort DSO when sales swing from month to month. The countback method works backward through recent months’ sales until the AR balance is used up.
Example: month-end AR is $500,000. Sales were $200,000 in March (31 days), $180,000 in February (28 days) and $250,000 in January (31 days).
- Subtract March sales: $500,000 − $200,000 = $300,000 remaining → count 31 days.
- Subtract February sales: $300,000 − $180,000 = $120,000 remaining → count 28 days.
- The remaining $120,000 is part of January: ($120,000 ÷ $250,000) × 31 = 14.9 days.
Countback DSO = 31 + 28 + 14.9 = 73.9 days.
What Does DSO Indicate?
DSO shows how quickly customers pay and how well the order-to-cash process converts sales into cash. It is a general indicator rather than a precise diagnosis: collections performance is only part of the story.
A high DSO can point to creditworthiness issues, invoicing errors, unresolved disputes and deductions, or weak collections discipline. A low DSO usually means fast collection, but an extremely low DSO may mean credit terms are so strict that they are limiting sales.
Context matters. Invoice timing, seasonality, quarter-end sales spikes, product or service disputes, and extended terms offered to close deals all move the number. Measuring DSO monthly and watching the trend is more useful than any single reading.
DSO is also an external signal. Investors and lenders watch DSO alongside revenue, and a rising DSO can raise questions about cash management and credit quality.
Why DSO Matters for CFOs
- Working capital: cash tied up in receivables cannot fund operations, pay down debt or finance growth.
- Bad debt risk: the longer an invoice stays unpaid, the less likely it is to be collected, and write-offs hit the P&L directly as bad debt expense.
- Investor and lender perception: a rising DSO can signal weakening cash management or customer credit quality.
- Cost of carry: for a business with $1 billion in annual credit sales, each extra day of DSO ties up about $2.7 million. At a 5% cost of capital, each extra DSO day costs about $137,000 a year.
How the Order-to-Cash Process Drives DSO
The whole order-to-cash (O2C) process shapes DSO. A company that invoices a week after shipping adds a week to DSO before collections even begins. Accurate, timely billing, disciplined and data-driven collections, and fast dispute resolution are rewarded with lower DSO. Customers tend to prioritize vendors who follow up consistently.
What Causes High DSO?
In enterprise accounts receivable, high DSO usually has three overlapping causes:
Process failures: manual invoicing that delays delivery, error-prone remittance matching that creates unapplied cash, and reactive dunning that contacts customers only after payment is overdue.
Data failures: no real-time view of which invoices are at risk, no prediction of customer payment behavior, and disconnected ERP, CRM and AR systems that create reconciliation delays.
Credit failures: onboarding customers without adequate credit risk assessment, extending terms beyond what a customer’s history supports, and missing early signs of financial distress.
These reinforce each other: manual processes create data gaps, data gaps weaken credit decisions, and weak credit decisions create the high-risk receivables that inflate DSO.
Best Possible DSO and Average Days Delinquent (ADD)
Best Possible DSO is what DSO would be if every customer paid exactly on the due date. It equals your payment terms: 30 days on Net 30, 60 days on Net 60, or a weighted average by revenue when terms vary.
Average days delinquent (ADD) is the gap between actual DSO and Best Possible DSO:
ADD = DSO − Best Possible DSO
For example, a company on Net 30 terms with a DSO of 42 days has an ADD of 12 days: customers pay 12 days late on average. ADD is the most actionable number for a collections team because it isolates lateness from the terms you chose to offer.
What Is a Good DSO?
A good DSO depends on your payment terms, industry and customer mix. Benchmark against your own terms first, then compare with what a good DSO looks like in your industry:
- Best-in-class organizations keep DSO within 10–15% of Best Possible DSO. On Net 30 terms, that is roughly 33–35 days.
- A DSO more than 50% above your payment terms (for example, above 45 days on Net 30) warrants immediate investigation.
- If more than 20% of receivables are more than 60 days past due, the collections process likely has a structural problem. Check your AR aging report.
DSO Benchmarks by Industry
DSO varies widely by industry because of differences in billing complexity, payment terms and sales cycles. According to Allianz Trade’s July 2026 report, global DSO was about 56.5 days in 2025, broadly stable since 2022. Use industry ranges as a rough guide and your own payment terms as the primary benchmark.
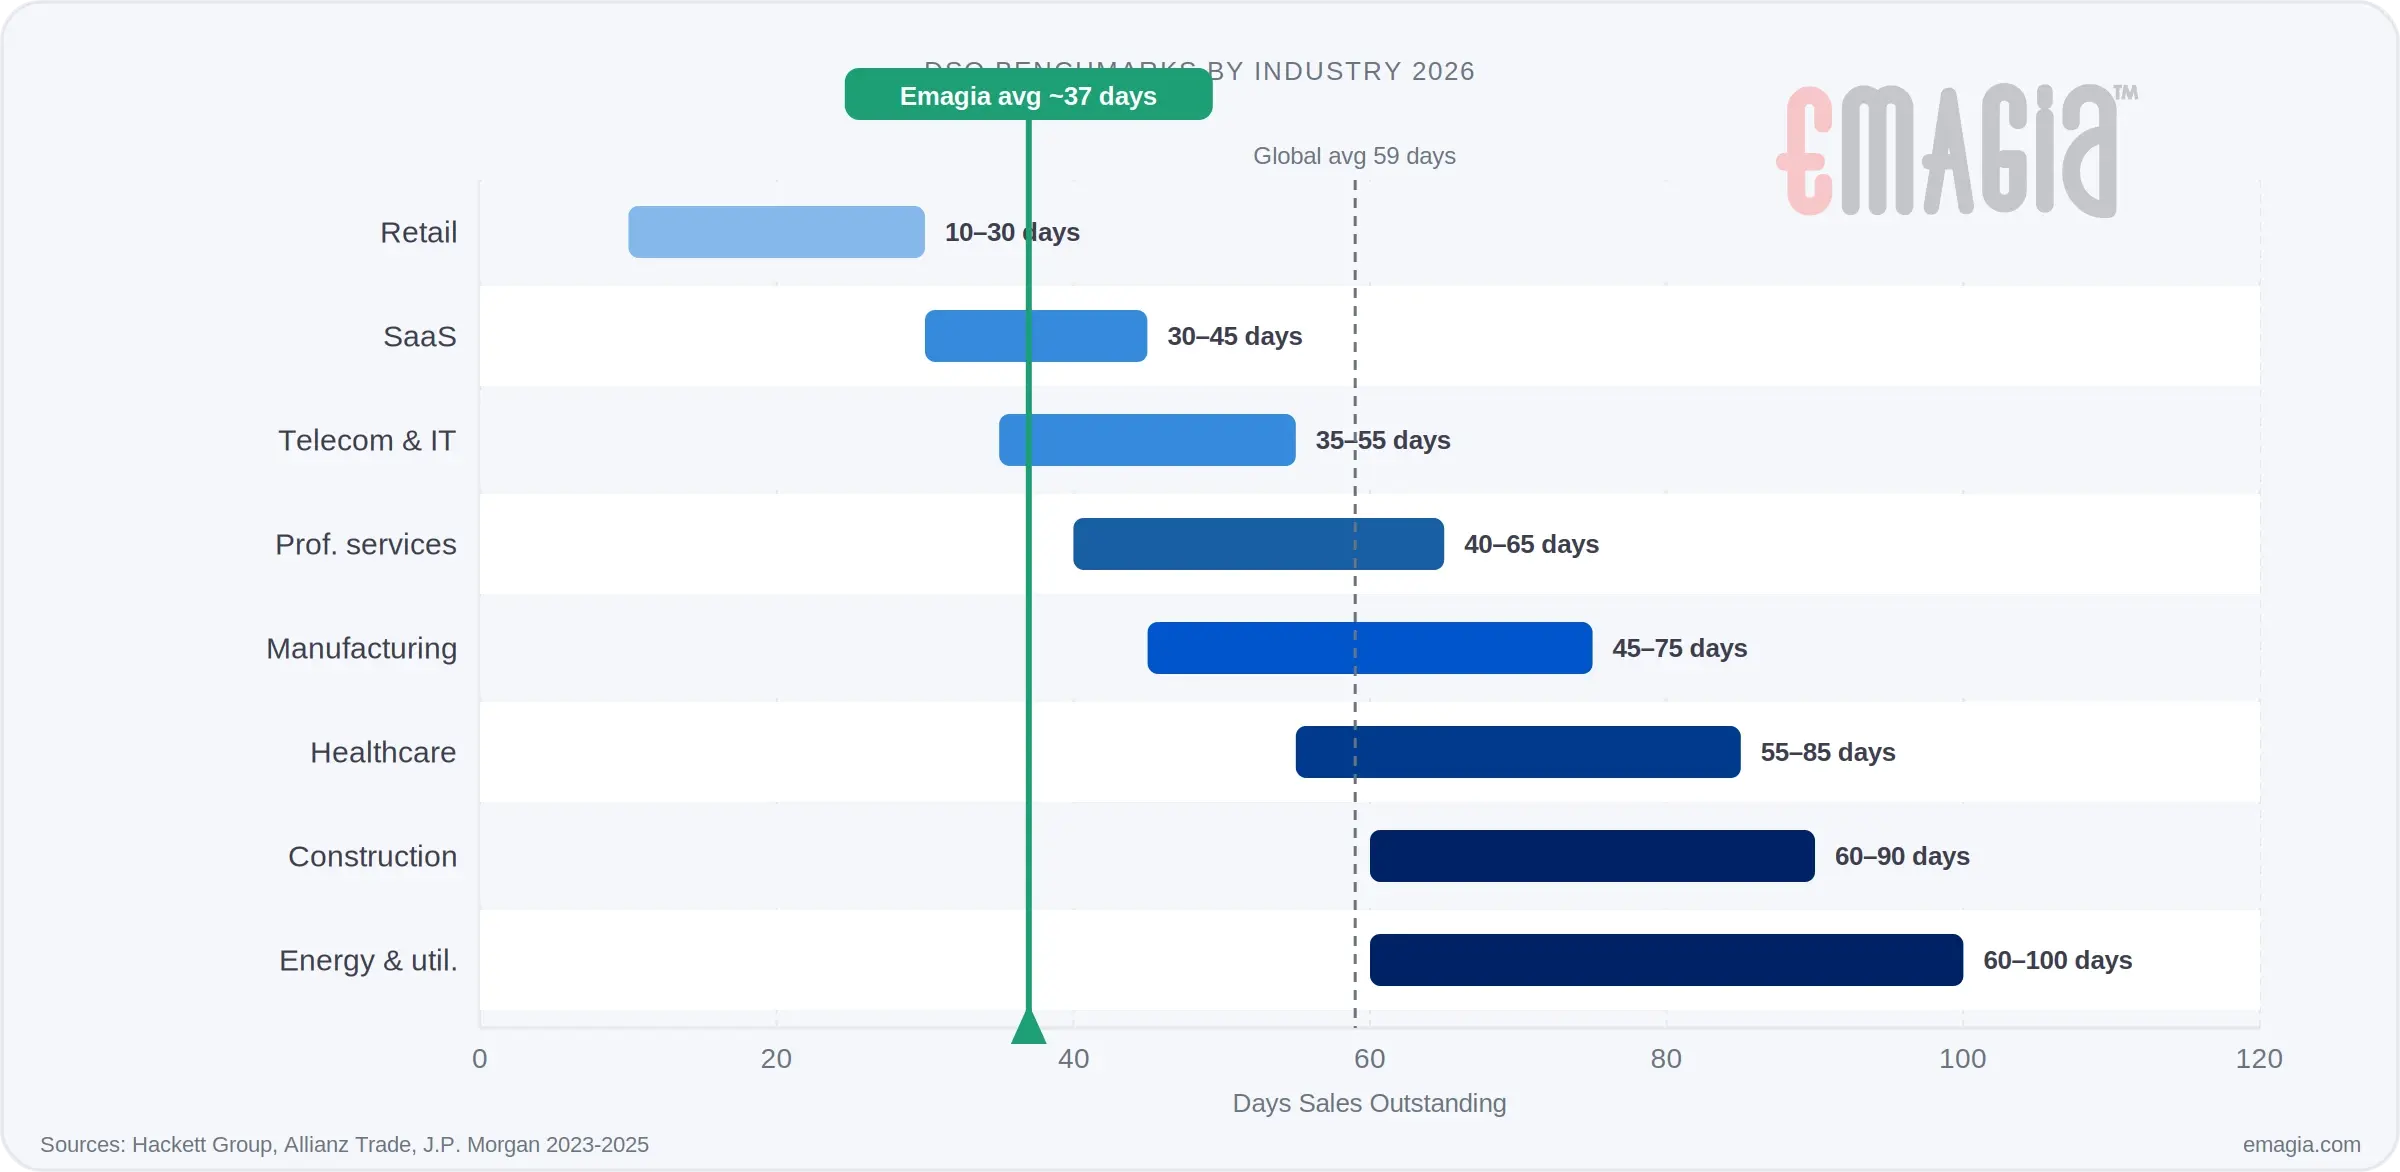
| Industry | Typical DSO range | Key driver |
|---|---|---|
| Retail & e-commerce | 10–30 days | Mostly point-of-sale; fast collection |
| Software / SaaS | 30–45 days | Annual prepayments compress DSO |
| Telecom & IT | 35–55 days | High volume, subscription complexity |
| Professional services | 40–65 days | Project-based billing |
| Manufacturing | 45–75 days | Complex billing, high invoice volume |
| Healthcare | 55–85 days | Insurance processing and claim delays |
| Construction | 60–90 days | Retention holdbacks extend cycles |
| Energy & utilities | 60–100 days | Long project and regulatory billing cycles |
Typical ranges compiled from public working capital studies [list and link the specific studies used]. Ranges vary by company size, region and methodology.
DSO vs. Other Accounts Receivable Metrics
| Metric | What it measures | Formula |
|---|---|---|
| Days sales outstanding (DSO) | Average days to collect after a sale | (AR ÷ Credit sales) × Days |
| Average days delinquent (ADD) | How late customers pay beyond terms | DSO − Best Possible DSO |
| AR turnover ratio | How many times AR is collected in a period | Net credit sales ÷ Average AR |
| Collection effectiveness index (CEI) | Share of collectible AR actually collected | (Beginning AR + Credit sales − Ending total AR) ÷ (Beginning AR + Credit sales − Ending current AR) × 100 |
| Cash conversion cycle (CCC) | Days to turn operating spend into cash | DSO + DIO − DPO |
DSO, DPO and DIO: The Cash Conversion Cycle
DSO is one of three components of the cash conversion cycle (CCC):
CCC = DSO + DIO − DPO
| Metric | What it measures | Goal |
|---|---|---|
| DSO: days sales outstanding | Time to collect from customers | Lower is better |
| DIO: days inventory outstanding | Time to sell inventory | Lower is better |
| DPO: days payable outstanding | Time to pay suppliers | Higher is better, within supplier terms |
For most B2B companies, DSO is the most directly controllable part of the CCC because it concerns cash already earned but not yet collected.
How to Reduce DSO
- Invoice immediately and accurately: automate invoice delivery so the payment clock starts on time.
- Tighten credit decisions: use credit risk assessment before extending terms.
- Remind before the due date: proactive reminders prevent lateness instead of chasing it.
- Prioritize collections by risk: use predictive collections to focus on accounts likely to pay late.
- Resolve disputes and deductions fast: streamline deductions management so short payments do not hold up cash.
- Apply cash quickly: automate cash application so payments do not sit as unapplied cash.
- Make paying easy: offer digital payment options and a self-service portal.
How AI-Powered AR Automation Reduces DSO
AI moves accounts receivable from rule-based workflows to predictive ones that catch problems before they inflate DSO. For the wider business case, see the benefits of accounts receivable automation. Emagia’s AI-powered order-to-cash platform brings O2C data into one place so every step works from the same, current information:
- Predictive collections prioritization: AI analyzes payment history, invoice age and customer signals to flag at-risk accounts before invoices become overdue.
- Dynamic dunning: AI chooses the timing, channel and tone of reminders for each customer based on past payment behavior.
- Automated cash application: Emagia’s cash application AI matches payments to open invoices automatically, with customers reporting auto-match rates above 90%.
- Faster credit onboarding: automated credit decisions shorten approval time so customers can be invoiced sooner.
- Self-service customer portal: customers view invoices, raise disputes and pay online without contacting AR.
- Real-time DSO dashboards: live DSO by business unit, region and customer segment for earlier intervention.
Emagia customers report DSO reductions of 20–30% (see customer results).
Factors That Affect DSO
- Customer payment behavior and creditworthiness
- Invoice accuracy and delivery timing
- Credit policies and payment terms
- Disputes, deductions and resolution time
- Collections strategy: reactive or predictive
- ERP and AR system integration and data quality
- Seasonal sales patterns and quarter-end effects
Key Takeaways
- DSO measures the average number of days to collect payment after a credit sale.
- Formula: (Accounts receivable ÷ Total credit sales) × Days in period. Use the countback method when sales are seasonal.
- A good DSO is within 10–15% of your payment terms; the gap is average days delinquent (ADD).
- Global DSO was about 56.5 days in 2025 (Allianz Trade), but your own terms are the better benchmark.
- Each extra DSO day ties up about $2.7 million per $1 billion of annual credit sales.
- Faster invoicing, proactive collections, quick dispute resolution and automated cash application all reduce DSO.
Frequently Asked Questions About DSO
What does DSO mean in finance?
DSO stands for days sales outstanding. It measures the average number of days a company takes to collect payment after making a credit sale. A lower DSO means faster cash conversion; a higher DSO signals collection delays, invoicing problems or credit risk.
How is DSO calculated?
DSO = (Accounts receivable ÷ Total credit sales) × Number of days in the period. For a quarter, divide receivables by the quarter’s credit sales and multiply by the number of days in the quarter (90 or 91). Include only credit sales, not cash or prepaid sales.
What is a good DSO?
A good DSO is within about 10–15% of your payment terms. On Net 30 terms, a DSO of roughly 33–35 days is strong; on Net 60, roughly 66–69 days. A DSO more than 50% above your terms needs investigation.
What is the average DSO?
According to Allianz Trade’s July 2026 report, global DSO was about 56.5 days in 2025. Averages vary widely by industry, region and company size, so compare DSO with your own payment terms first.
What causes high DSO?
High DSO is usually caused by late or inaccurate invoices, reactive collections, unresolved disputes and deductions, slow cash application that leaves payments unapplied, loose credit terms, and customers in financial difficulty.
Is a high or low DSO better?
Lower is generally better because it means faster collection and more available cash. However, an extremely low DSO can mean credit terms are too strict and may be limiting sales.
What is the difference between DSO and ADD?
DSO measures the average days to collect payment. Average days delinquent (ADD) measures how late customers pay beyond their terms: ADD = DSO − Best Possible DSO.
How can automation reduce DSO?
AR automation reduces DSO by sending invoices immediately, reminding customers before due dates, prioritizing at-risk accounts, resolving disputes faster and matching payments automatically so cash is applied quickly.
How often should companies measure DSO?
Most companies measure DSO monthly and review the trend over at least six months. Quarterly DSO is useful for board reporting and benchmarking. A steady rise over several months matters more than a single spike.
Sources
- Allianz Trade, Global cash conversion cycle report, July 2026 (global DSO 56.5 days and CCC 67 days in 2025).
- Allianz Trade, Global DSO and working capital report, April 2024 (global DSO 59 days in 2023).
- Emagia, customer case study.
See How Emagia Reduces DSO for Global Enterprises
Emagia’s AI-powered order-to-cash platform helps enterprise finance teams release working capital by removing the manual bottlenecks that inflate DSO.
Recognized by Gartner (Visionary), IDC and Everest Group (Leader) for AR automation.