Credit Risk Automation: AI-Native Credit Risk Assessment, Decisioning & Monitoring
Credit Risk Automation uses AI, machine learning, predictive analytics, and automated workflows to assess, approve, monitor, and manage customer credit risk. It replaces manual credit reviews with real-time risk scoring, policy-driven decisioning, continuous monitoring, and automated alerts—helping enterprise finance teams make faster, more consistent credit decisions while improving risk visibility and working capital control.
What Is Credit Risk Automation?
Credit Risk Automation is the use of AI-powered technology to automatically assess, approve, monitor, and manage customer credit risk using financial, behavioral, payment, and external data. Instead of relying primarily on spreadsheets, manual reviews, and periodic assessments, automated credit risk systems use predictive models, business rules, workflows, and continuous monitoring to support faster and more consistent decisions.
A modern Credit Risk Automation solution typically includes:
- AI-driven probability of default (PD) modeling
- Automated credit approvals and credit limit adjustments
- Continuous credit risk monitoring and early warning alerts
- ERP- and CRM-integrated credit decision workflows
- Automated data aggregation and normalization
- Risk dashboards, analytics, and audit-ready reporting
For CFOs and finance leaders, Credit Risk Automation can help standardize credit policies, accelerate customer onboarding, identify emerging risk earlier, and improve visibility into credit exposure and working capital.
These capabilities support the broader credit risk management process across the enterprise.
Why Does Credit Risk Automation Matter for CFOs?
Credit risk directly affects revenue, cash flow, bad debt, customer relationships, and working capital. When credit assessments depend heavily on manual processes, finance teams may struggle to evaluate large customer portfolios consistently or respond quickly when risk conditions change.
Credit Risk Automation helps finance organizations move from periodic, manual credit reviews toward continuous, data-driven risk management.
| Enterprise KPI or Area | How Credit Risk Automation Helps |
|---|---|
| Days Sales Outstanding (DSO) | Supports proactive credit decisions and exposure management that can contribute to healthier receivables performance. |
| Bad Debt | Uses predictive risk signals and early warnings to help identify accounts requiring intervention. |
| Credit Approval Cycle Time | Automates data gathering, scoring, routing, and policy-based decisions to reduce manual bottlenecks. |
| Working Capital | Improves visibility into customer exposure and credit-related risks that influence cash flow predictability. |
| Credit Team Productivity | Reduces repetitive data collection and review activities so analysts can focus on exceptions and strategic risk decisions. |
For global enterprises, integrating Credit Risk Automation into the broader Order-to-Cash environment can help standardize credit policies, improve exposure visibility, and support consistent decision-making across regions.
Enterprise teams can use advanced credit risk solutions to strengthen risk management and support more proactive credit decisions.
How Does Credit Risk Automation Work?
Credit Risk Automation combines data integration, AI-powered risk assessment, automated decisioning, and continuous monitoring into a connected workflow.
- Data Aggregation: Internal ERP data, payment history, financial information, customer records, and relevant external data are brought together.
- AI Risk Assessment: AI and machine learning models evaluate risk indicators and can calculate measures such as probability of default (PD), loss given default (LGD), exposure at default (EAD), and risk grades.
- Automated Decisioning: Credit applications and accounts are evaluated against configured policies, risk thresholds, and approval rules.
- Exception Management: Higher-risk or unusual cases can be routed to credit analysts for human review.
- Continuous Monitoring: Changes in payment behavior, financial conditions, exposure, or other risk indicators can trigger alerts and reassessment.
- Reporting and Optimization: Dashboards and analytics provide visibility into portfolio risk, credit decisions, exceptions, and performance.
Core Features of Credit Risk Automation
- Real-time AI credit scoring and probability of default modeling
- Automated credit limit management and approvals
- Policy-driven credit decision workflows
- Continuous portfolio risk monitoring
- Early warning alerts and anomaly detection
- ERP and CRM integration
- Credit exposure dashboards and analytics
- Audit-ready compliance reporting
Key Pillars of an Effective Credit Risk Automation Solution
An effective Credit Risk Automation platform combines data, AI, workflow automation, monitoring, and analytics to create a proactive approach to managing enterprise credit exposure.
1. Automated Data Ingestion and Normalization
Reliable credit decisions depend on having accurate and accessible data. Automation can consolidate information from multiple internal and external sources into a standardized data foundation.
- Data Connectors: Connect internal systems and relevant external data sources such as financial information, credit scores, payment histories, public records, and other approved risk data.
- Data Cleansing and Normalization: Standardize data from different systems and formats so it can be consistently analyzed.
- Intelligent Document Processing: AI-powered OCR and NLP can extract relevant information from structured and unstructured documents, reducing manual data entry.
This provides credit analysts with a more consistent view of customer information and risk indicators.
2. Intelligent Credit Scoring and Assessment
AI and machine learning can move credit assessment beyond static, periodic reviews toward more dynamic risk evaluation.
- AI/ML Credit Models: Models can evaluate factors associated with probability of default (PD), loss given default (LGD), and exposure at default (EAD).
- Dynamic Credit Scoring: Credit scores can be updated as new financial, payment, or behavioral information becomes available.
- Predictive Risk Analytics: Historical and current data can be analyzed to identify potential deterioration and emerging risk signals.
This supports more informed and timely credit decisions. Related credit risk modelling approaches can provide the analytical foundation for automated assessment.
3. Automated Workflow and Decisioning
Workflow automation helps organizations apply credit policies consistently while reducing manual handoffs and approval bottlenecks.
- Automated Application Processing: Validate customer information and initiate credit assessments using predefined workflows.
- Rule-Based Automation: Trigger credit limit reviews, reassessments, escalations, or other actions based on configured criteria.
- Tiered Approval Workflows: Route applications and exceptions to the appropriate approval level based on risk, exposure, or business rules.
This creates a more standardized credit decision process while keeping human review available for complex exceptions.
4. Continuous Monitoring and Early Warning Systems
Credit risk can change after an account has been approved. Continuous monitoring helps finance teams identify changes in risk rather than waiting for the next scheduled review.
- Portfolio Surveillance: Monitor customer and portfolio risk indicators continuously or at configured intervals.
- Anomaly Detection: Identify unusual patterns that may indicate emerging financial or payment risk.
- Proactive Alerts: Notify credit teams when risk scores change, exposure thresholds are reached, or other configured conditions occur.
This supports earlier intervention and more proactive exposure management.
5. Integrated Reporting and Analytics
Credit Risk Automation should turn operational data into actionable information for both credit teams and finance leadership.
- Customizable Dashboards: Monitor credit risk metrics, portfolio concentrations, exposure, and trends.
- Performance Tracking: Evaluate decision speed, approval rates, risk outcomes, and mitigation activities.
- Drill-Down Analysis: Investigate individual customers, segments, industries, or portfolios.
- Reporting: Generate standardized reports and maintain appropriate records for audit and governance purposes.
Credit Risk Automation vs. Traditional Credit Management
The primary difference is how credit decisions are supported. Traditional processes often depend on periodic reviews, manual data collection, and analyst-driven workflows, while automated approaches combine real-time data, predictive analytics, business rules, and continuous monitoring.
| Capability | Traditional Credit Management | AI-Powered Credit Risk Automation |
|---|---|---|
| Data Sources | Primarily historical financial and customer information | Integrated internal, external, payment, and behavioral data |
| Decision Process | Manual review and approval | Automated decisioning with configurable human review |
| Risk Monitoring | Periodic assessments | Continuous or event-driven monitoring |
| Scalability | Dependent on analyst capacity | Designed to support larger portfolios through automation |
| Risk Detection | Often reactive | Predictive and proactive risk identification |
| Governance | Manual documentation and controls | Workflow controls, audit trails, and automated reporting |
These capabilities can be evaluated using relevant credit risk metrics, including probability of default, exposure measures, approval performance, and portfolio risk indicators.
What Are the Enterprise Use Cases for Credit Risk Automation?
Global Shared Services Centers
Standardize credit policies and workflows across regions while reducing manual inconsistencies between teams.
High-Volume B2B Enterprises
Automate repetitive credit assessments and reviews across large customer portfolios without relying entirely on additional manual capacity.
High-Growth Companies
Scale customer onboarding and credit approvals while maintaining defined risk policies and approval controls.
Regulated Industries
Support controlled workflows, audit trails, documentation, and model governance requirements.
Industries That Can Benefit
- Manufacturing
- Distribution
- Technology and SaaS
- Telecommunications
- Healthcare
- Financial Services
Benefits of Credit Risk Automation
1. Improved Accuracy and Reduced Manual Errors
Automating data collection, validation, calculations, and workflow steps can reduce errors associated with repetitive manual processing. Consistent rules and standardized workflows also improve process consistency.
2. Faster Credit Decisions and Customer Onboarding
Automated data gathering, risk scoring, and approval routing can reduce unnecessary delays in credit assessments. Faster decisions can help businesses respond more efficiently to new customer and order opportunities.
3. Greater Operational Efficiency
Credit analysts spend less time gathering information and performing repetitive checks. This allows teams to focus more on complex accounts, exceptions, customer risk analysis, and strategic activities.
4. Proactive Risk Mitigation
Continuous monitoring and predictive analytics can help identify deteriorating accounts or emerging risk signals earlier. Finance teams can then review credit limits, payment terms, exposure, or collection actions as appropriate.
Modern credit risk solutions support this proactive approach to exposure and loss management.
5. Enterprise Scalability
Automated platforms can support larger customer portfolios and higher transaction volumes without requiring every credit review to be performed manually.
6. Better Risk Visibility and Predictive Insights
AI and analytics can combine multiple data points to provide a more forward-looking view of customer and portfolio risk. This can help finance leaders identify patterns that may not be obvious through isolated manual reviews.
7. Better Customer Experience
Faster and more consistent credit decisions can simplify customer onboarding and reduce unnecessary delays while maintaining appropriate risk controls.
Credit Risk Automation Maturity Model
Organizations can view Credit Risk Automation as a maturity journey rather than a single technology implementation.
- Level 1 – Manual: Spreadsheet-based reviews, manual data collection, and static credit policies.
- Level 2 – Rule-Based: Basic workflow automation and predefined scoring or decision rules.
- Level 3 – Predictive AI: Machine learning and predictive models support probability of default and risk assessment.
- Level 4 – Intelligent/Autonomous Credit: Real-time decisioning, continuous monitoring, dynamic risk evaluation, and human oversight for exceptions.
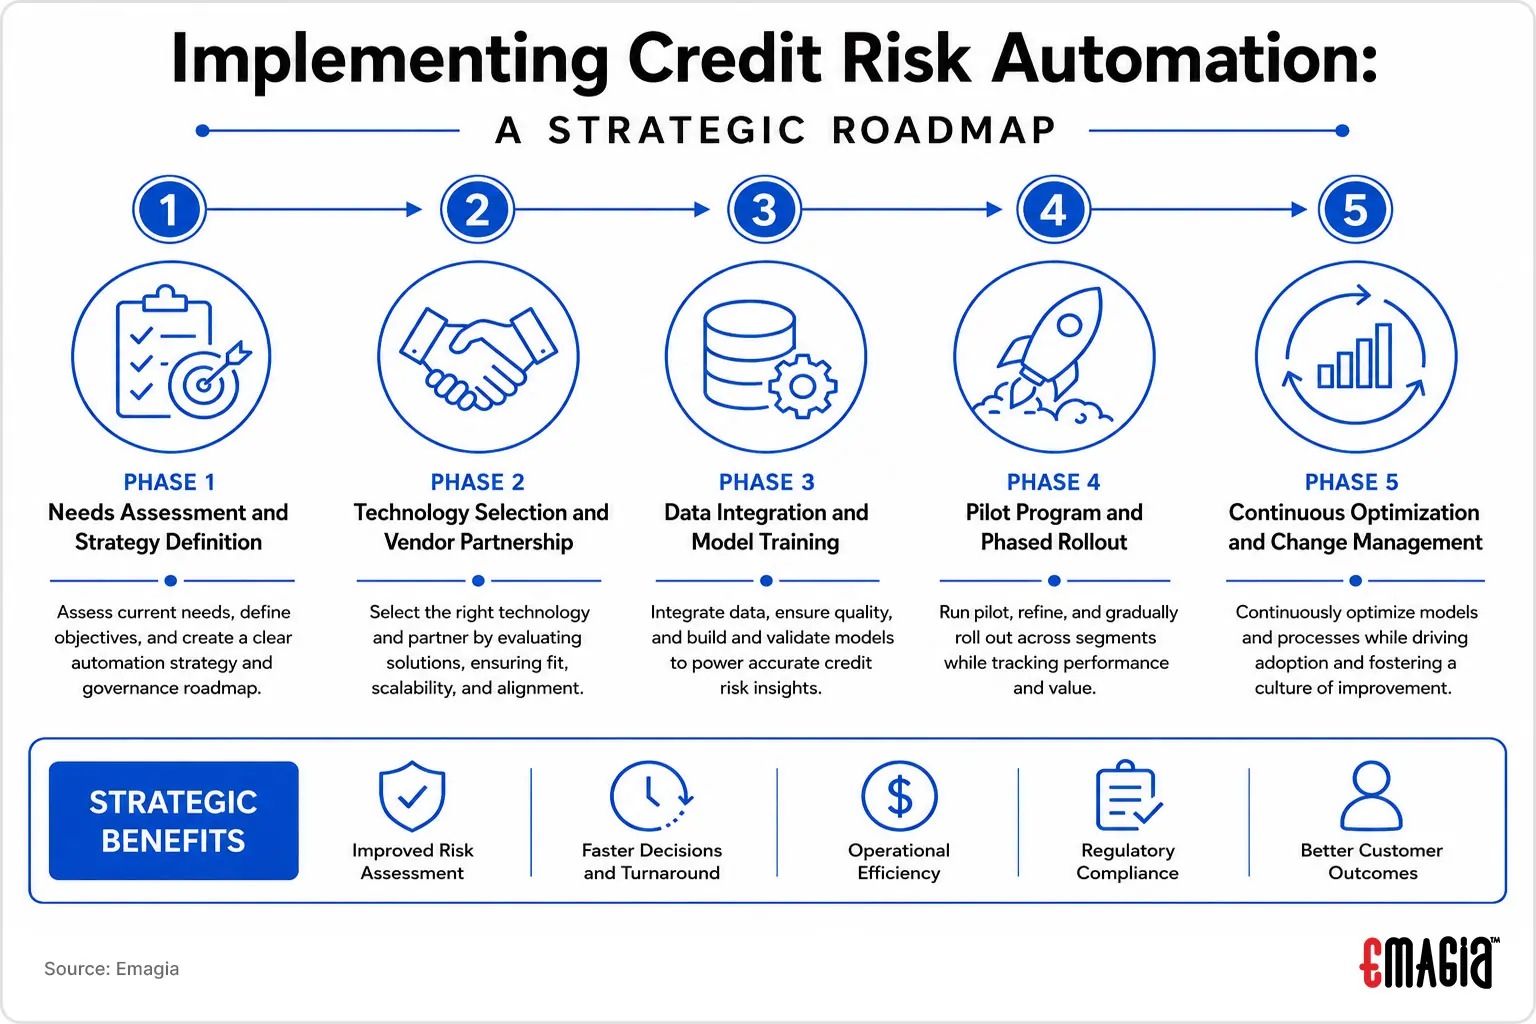
How to Implement Credit Risk Automation: A Strategic Roadmap
Successful Credit Risk Automation requires more than deploying software. Organizations should establish clear objectives, prepare data, define governance, integrate core systems, and introduce automation in controlled stages.
Phase 1: Assess Current Processes and Define Objectives
- Document manual credit processes, bottlenecks, exceptions, and operational challenges.
- Define measurable business objectives for approval speed, automation, risk management, and productivity.
- Assess the quality, accessibility, and ownership of existing credit data.
- Establish a cross-functional team involving Credit, Finance, IT, Sales, and other relevant stakeholders.
Phase 2: Select the Technology and Vendor
- Platform Capabilities: Evaluate data integration, AI/ML capabilities, workflow automation, monitoring, analytics, and reporting.
- Integration: Confirm compatibility with existing ERP, CRM, Order-to-Cash, and finance systems.
- Scalability and Security: Evaluate whether the platform can support current and future business requirements while meeting security and compliance expectations.
- Implementation Support: Review implementation methodology, training, support, and ongoing optimization capabilities.
Phase 3: Integrate Data and Configure Models
- Connect internal and approved external data sources.
- Map, cleanse, and normalize data for consistent analysis.
- Train and validate AI/ML models using appropriate historical data.
- Maintain human-in-the-loop validation where appropriate.
- Configure credit decisioning software and monitoring workflows according to approved credit policies.
Phase 4: Pilot and Roll Out in Stages
- Begin with a defined customer segment, product, region, or use case.
- Measure performance and collect feedback from credit users.
- Refine models, rules, workflows, and exception handling.
- Expand gradually once the solution has demonstrated operational readiness.
Organizations can then extend the Credit Risk Automation solution to more business units and customer segments.
Phase 5: Continuously Optimize
- Monitor KPIs and business outcomes.
- Review model performance and recalibrate when necessary.
- Monitor data quality and changes in risk patterns.
- Train credit teams on new workflows and responsibilities.
- Maintain appropriate governance over automated decisions.
Challenges of Credit Risk Automation
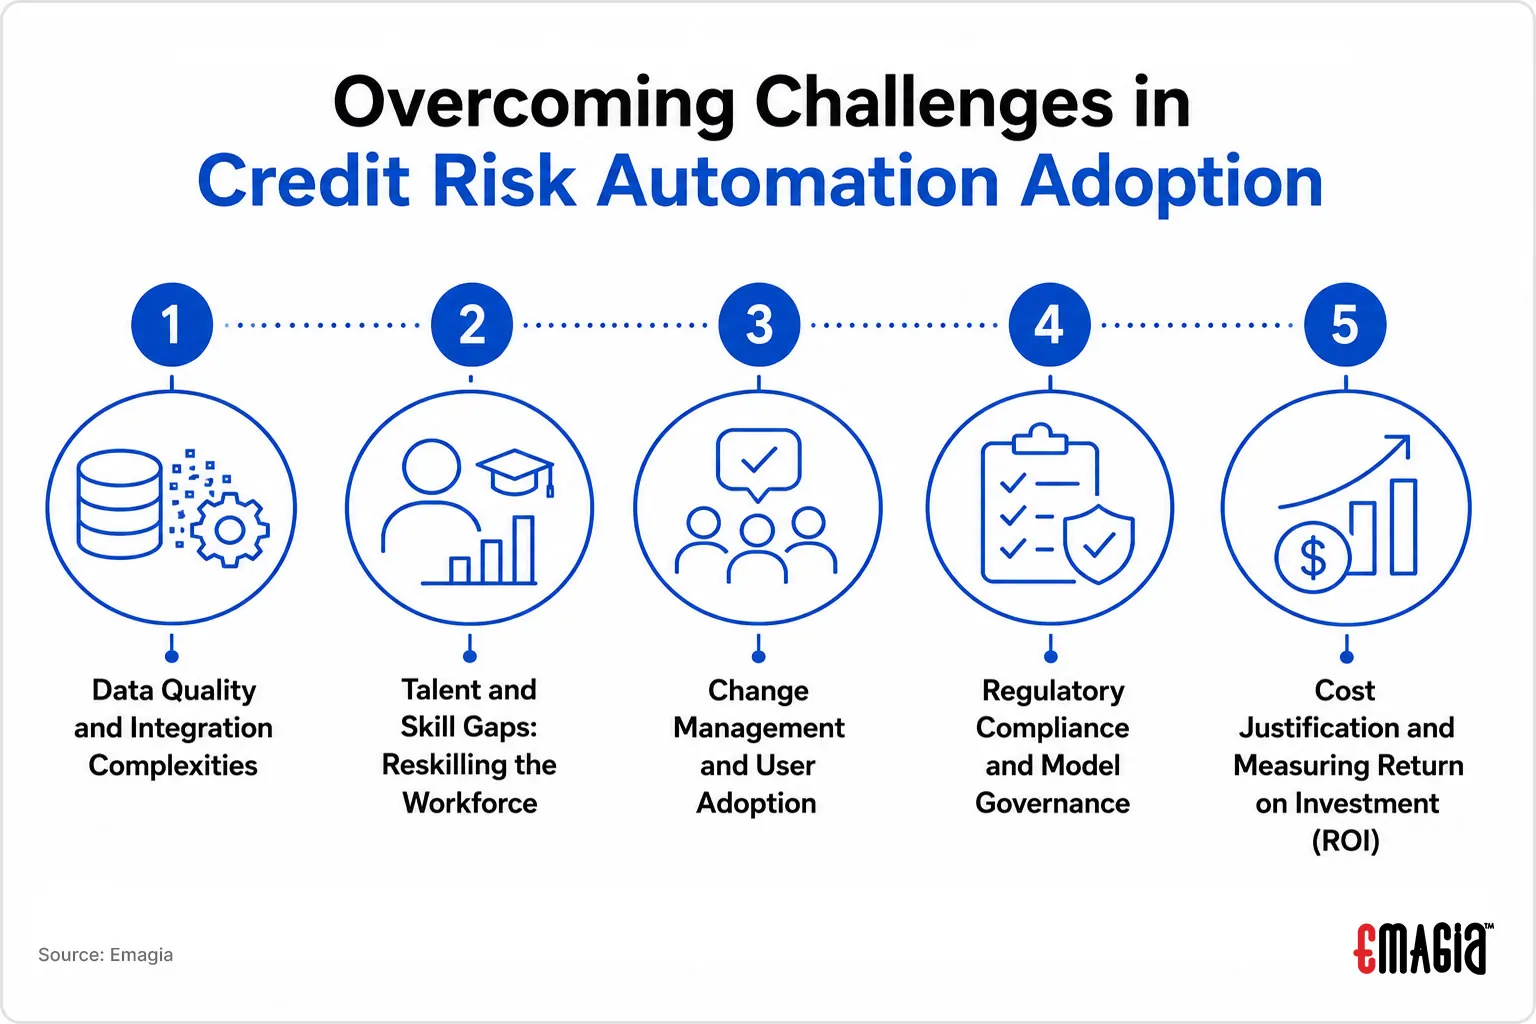
Credit Risk Automation can improve efficiency and visibility, but implementation requires careful attention to data, people, technology, governance, and business processes.
1. Data Quality and Integration
Inconsistent, incomplete, duplicated, or siloed data can reduce the effectiveness of automated risk assessment. Organizations should establish data governance, integration, validation, and normalization processes before relying heavily on automated decisions.
2. Skills and Workforce Transformation
Automation changes the role of credit analysts. Instead of spending most of their time collecting and validating information, analysts increasingly focus on interpreting risk insights, managing exceptions, reviewing complex accounts, and supporting model governance.
3. Change Management and User Adoption
Successful adoption requires clear communication, practical training, stakeholder involvement, and measurable improvements. Credit teams should understand how automated recommendations are generated and when human intervention is required.
4. Regulatory Compliance and Model Governance
AI-driven credit decisions require appropriate controls around transparency, explainability, bias, validation, documentation, and ongoing monitoring. Organizations should align automation with the regulatory and governance requirements applicable to their business and markets.
5. Measuring ROI
Organizations should establish a business case before implementation and measure outcomes such as manual effort, approval cycle time, exception rates, credit losses, portfolio performance, and productivity. ROI should be evaluated using the organization’s own baseline and verified results rather than generic industry claims.
Credit Risk Automation Technology Stack
A modern Credit Risk Automation architecture typically combines several technologies:
- Data Integration: Connects ERP, CRM, credit bureau, financial, payment, and other approved data sources.
- Artificial Intelligence and Machine Learning: Supports predictive risk assessment, pattern recognition, anomaly detection, and scoring.
- Robotic Process Automation: Automates repetitive, rule-based activities such as data extraction, validation, and system updates.
- Analytics and Business Intelligence: Provides dashboards, portfolio analysis, risk reporting, and decision insights.
- Workflow Automation: Routes applications, approvals, exceptions, reviews, and risk events according to configured policies.
Regulatory Alignment and AI Model Governance
Enterprise Credit Risk Automation requires governance controls appropriate to the organization’s regulatory environment and risk framework. Depending on the business and jurisdiction, relevant considerations may include IFRS 9, Basel requirements, SOX controls, data protection obligations, model validation, and internal risk policies.
Key governance capabilities can include:
- Documented credit policies and decision rules
- Audit trails for automated and human decisions
- Model validation and performance monitoring
- Explainability of AI-assisted decisions
- Bias and fairness monitoring where applicable
- Human oversight for defined exceptions and high-risk decisions
- Controlled model and workflow changes
How Emagia Enables AI-Native Credit Risk Automation
Emagia’s AI-native Order-to-Cash platform brings credit, receivables, cash application, and collections together within an intelligent finance ecosystem. By combining predictive credit assessment with payment and receivables insights, enterprises can improve visibility into customer risk and credit exposure.
- AI-based probability of default modeling
- Dynamic credit limit optimization
- Continuous portfolio monitoring
- ERP-integrated credit workflows
- Real-time risk dashboards
This approach connects credit risk management with the wider Order-to-Cash lifecycle, helping finance teams make credit decisions using a broader view of customer financial and payment behavior.
Frequently Asked Questions About Credit Risk Automation
What is Credit Risk Automation?
Credit Risk Automation uses AI, machine learning, data integration, and automated workflows to assess, approve, monitor, and manage customer credit risk. It reduces reliance on manual credit reviews and supports more consistent, data-driven decisions.
How does AI improve credit risk assessment?
AI can analyze large and diverse datasets, identify patterns associated with credit risk, calculate predictive risk indicators, and generate alerts when risk conditions change. Human review can remain part of the process for complex or high-risk cases.
How does Credit Risk Automation help reduce bad debt?
Credit Risk Automation can help identify high-risk customers earlier, monitor changes in risk, and support proactive actions such as credit limit reviews, payment-term adjustments, or escalation to collections. Actual bad debt improvement depends on data quality, business policies, implementation, and execution.
Can Credit Risk Automation integrate with ERP systems?
Yes. Enterprise credit automation platforms can integrate with ERP and CRM environments so credit information and decisions can be incorporated into customer onboarding, order processing, and broader Order-to-Cash workflows. Integration capabilities vary by platform and implementation.
Is Credit Risk Automation suitable for mid-sized companies?
Yes. Cloud-based automation can support both mid-market and enterprise organizations. The appropriate solution depends on customer volume, risk complexity, integration requirements, governance needs, and available data.
What data is used for automated credit risk assessment?
Depending on the organization and solution, data can include financial information, payment history, credit bureau information, customer exposure, ERP records, behavioral indicators, and other approved external risk data.
Does Credit Risk Automation replace credit analysts?
Not necessarily. The strongest operating models use automation to handle repetitive assessment and workflow activities while credit professionals manage exceptions, interpret complex risks, oversee policies, and govern automated decision models.
How does Credit Risk Automation support working capital?
By improving credit decision speed, monitoring customer exposure, identifying emerging risk, and supporting proactive credit management, automation can contribute to more predictable receivables performance and working capital management.
Conclusion: Building a More Intelligent Credit Risk Management Process
Credit Risk Automation represents a shift from periodic, manual credit reviews toward continuous, data-driven risk management. By combining AI-powered assessment, automated decision workflows, real-time monitoring, predictive analytics, and human oversight, organizations can create a more scalable and consistent approach to customer credit risk.
For enterprise finance teams, the value extends beyond faster credit decisions. A well-designed Credit Risk Automation strategy can improve risk visibility, support proactive exposure management, increase credit team productivity, and connect credit decisions more closely with the broader Order-to-Cash and working capital strategy.


